
Small Group Health Insurance: Key Coverage Options For Employers And Teams

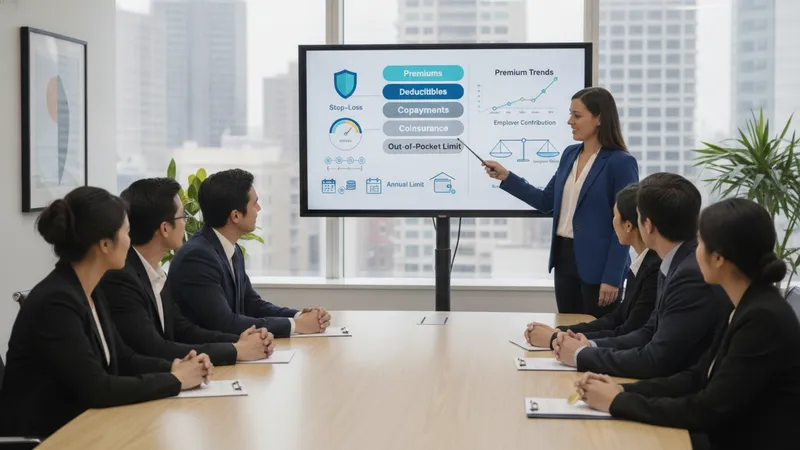
Cost-Sharing, Premiums, and Out-of-Pocket Limits for Small Group Health Insurance: Key Coverage Options for Employers and Teams
Cost-sharing features define how expenses are split when care is used and include premiums, deductibles, copayments, and coinsurance. Employers typically decide a contribution strategy for premiums that can be a fixed dollar amount or a percentage of the premium; employees cover the remaining premium portion. Deductibles set the threshold before certain benefits are paid by the plan, while copayments and coinsurance determine member costs per service. Out-of-pocket limits cap a member’s total annual liability, providing a form of financial protection. The combination of these features shapes both member financial exposure and the employer’s predictable budget for benefit costs.
Premium trends and predictability are central budgeting concerns for small groups. Premiums may change at renewal based on claims experience, market trends, and plan design changes. Employers exploring alternative funding mechanisms may consider level-funded or partially self-funded approaches that aim to stabilize monthly payments while allowing for potential refunds or higher costs depending on actual claims. Stop-loss insurance is commonly used with self-funding to limit the employer’s exposure to unusually large claims. These funding choices influence cash flow expectations and the allocation of financial risk between employer and plan members.
Design choices can be used to manage both costs and member behavior. Higher deductibles and coinsurance can reduce premium levels but may increase financial barriers to care for some members. Conversely, lower member cost-sharing can encourage earlier use of preventive services and routine care, which may influence longer-term utilization patterns. Benefit design elements such as preventive care coverage without cost-sharing, tiered provider networks, and targeted cost-management programs are tools that can affect how and when care is accessed. Employers often consider the interplay of these levers relative to workforce needs and financial constraints.
Prescription drug cost-management typically supplements medical cost-sharing design and can significantly influence overall plan costs. Strategies include formulary tiering, utilization management protocols, mail-order incentives, and negotiated rebates or discounts within pharmacy benefit management arrangements. Employers reviewing options may consider typical medication use among their enrolled population as part of plan selection. These considerations are pragmatic assessments rather than performance guarantees; actual impact on costs depends on utilization, negotiated terms, and regulatory environments that vary by jurisdiction.