
Secured Business Credit Cards: Building Business Credit With A Security Deposit

A secured business credit card is a business payment account backed by a refundable security deposit that an issuer holds to reduce lending risk. The deposit usually establishes or caps the available credit line and may be returned when the account is closed or converted to an unsecured product. Issuers typically use the account activity and payment history to assess ongoing creditworthiness, and some report activity to business-oriented credit bureaus. The arrangement is often used by small enterprises or sole proprietors that seek a credit account while they build a documented track record of on-time payments and controlled usage.
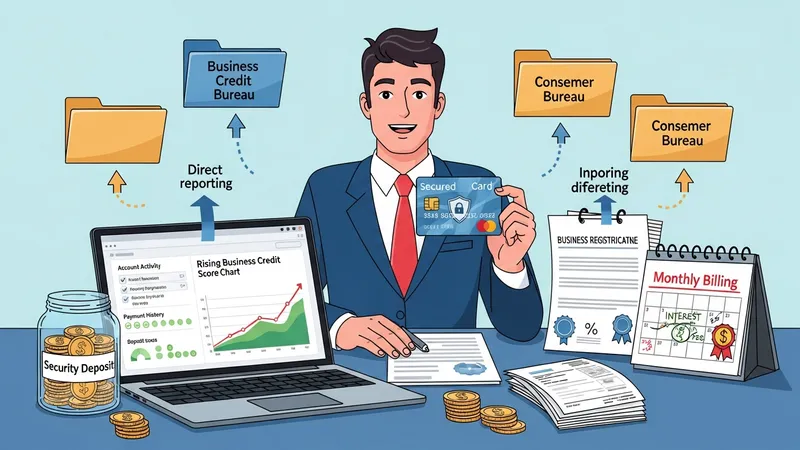
Account setups vary: some issuers accept deposits equal to the requested limit, while others set the limit at a portion of the deposit. Requirements for identity, business registration, and tax identifiers can differ by provider. Monthly billing, interest rates, and fee schedules may apply and are disclosed in account agreements. Reporting practices also vary; an account that reports to major business credit repositories may contribute to a credit history for the business entity, whereas accounts that report only to consumer bureaus may primarily affect the owner’s personal file.
- Community bank secured business card — Typically offered by regional banks with deposit-to-limit structures and documentation requirements; deposit ranges often span from a few hundred to several thousand dollars depending on the issuer.
- Credit union secured business card — Issued by member-owned institutions that may set more conservative deposit requirements and local underwriting criteria; these products often emphasize relationship-based evaluation.
- Fintech or online secured business card — Digital issuers that may combine a held deposit with account features for expense tracking and may vary in whether they report to business credit bureaus or consumer credit agencies.
Eligibility for a secured business credit card often depends on basic identity verification and business details such as tax identifiers or registration. For sole proprietors, issuers may request the owner’s personal information alongside business data. Underwriting may consider prior credit history, existing business accounts, and the intended deposit amount. Some lenders may set minimum and maximum deposit thresholds and may require documentation of business activity. Small enterprises that lack established trade credit often use secured cards as an early method to create a documented payment history that may later support broader credit access.
Deposit amounts and how they map to the credit limit can vary notably between issuers. One common model is a one-to-one relationship where a deposited amount directly equals the credit limit; another model sets limits at a fraction of the deposit. Deposit size may influence approval odds and available spending capacity. Issuers typically hold deposits in designated accounts and describe refund conditions in the account agreement. When considering typical ranges, many secured products start with deposits of a few hundred units of local currency and may extend to several thousand for larger lines.
Reporting practices are an important distinction across secured business cards. Some accounts report to commercial credit bureaus such as Dun & Bradstreet, Experian Business, or Equifax Commercial, which may help establish a business credit file over time. Other products report primarily to consumer credit agencies and thereby affect the owner’s personal credit profile. Whether an issuer reports account activity and which bureau receives the data can influence how the account contributes to building a business credit presence. It is common for reporting policies to be disclosed in provider materials or account terms.
Responsible account management practices can influence the utility of a secured business card for establishing credit history. Regular, on-time payments often produce the clearest record of creditworthiness; high utilization ratios can signal risk on credit reports. Maintaining clear bookkeeping, separating personal and business transactions, and reconciling statements may support accurate reporting and financial clarity. Over time, consistent payment behavior may lead some issuers to offer product changes or to refund the security deposit while adjusting the account’s terms, although outcomes vary with issuer policy and the business’s credit performance.
In summary, a secured business credit card uses a refundable deposit as collateral to create a controlled credit line for business use. Variations include deposit-to-limit mapping, reporting to different credit repositories, and differing fee structures and eligibility requirements. These factors may influence how effectively an account builds a business credit history. The next sections examine practical components and considerations in more detail.